



Are You Ready? A 2027 Readiness Check
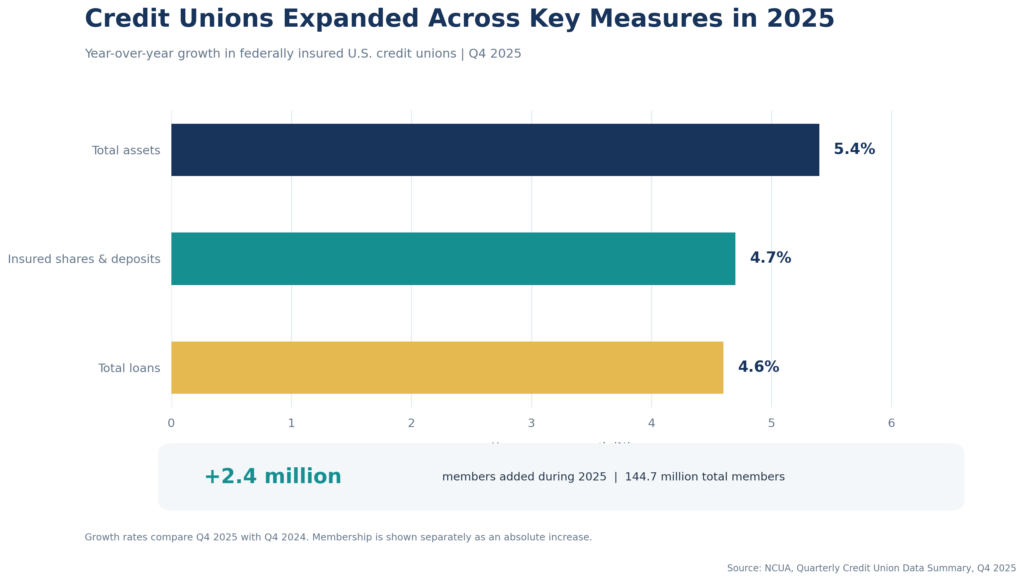
- Deposit Growth: Is digital account opening frictionless, with instant funding available at opening?
- Digital Personalization: Are distinct member segments receiving distinct, measured outreach?
- AI Use: Is at least one AI use case live in production, with documented governance and human oversight?
- Faster Payments: Is the institution live on FedNow receive, with a send timeline defined and fraud controls updated for instant finality?
- Fraud Prevention: Is staff training scenario-based, recurring, and current on AI-enabled impersonation and social-engineering threats?
- New Revenue: Does every new revenue initiative pass a mission-alignment review before launch?
- Efficiency: Are both cost savings and member-experience outcomes measured for every automation initiative?
1. Deposit Growth Is a Competitive Battleground Now
2. Generic Digital Banking Is No Longer Competitive
Access to digital banking is now a given. What determines competitive standing in 2027 is relevance. Members can already log in, check balances, and transfer funds. What they increasingly expect is an experience that actually knows them.
3. AI Without Data Governance Is a Liability, Not an Advantage
A September 2026 study reported by The Financial Brand, based on interviews with 46 credit-union executives through Stanford Graduate School of Business, found a significant gap between confidence and readiness. Executives rated AI readiness 3.3 out of 5, but frontline data visibility 3.0 and workflow support 2.8. Self-assessed readiness correlated only weakly with data foundations. Meanwhile, 45 of 46 executives said control of member data was important, while describing fragmented systems and uncertainty over data ownership.
What credit unions should do: Audit current and planned AI use, including features embedded in vendor platforms. Document the data used, who reviews outputs, how errors are caught, and how members can seek recourse. Start with one or two lower-risk use cases: member-service automation, unusual-transaction flagging, or campaign targeting.
4. Faster Payments Are No Longer Optional Infrastructure
- Compliance: Instant finality changes dispute resolution. Reversals work differently on real-time rails, and teams need updated protocols.
- Fraud: Controls must flag suspicious transactions before funds leave, not after. The window to intervene is seconds, not hours.
- Member communications: Members need clear explanations of what instant payments mean for them, including what happens when something goes wrong.
- Core systems: Configurations may need updating to reflect near-real-time posting and balance availability.
5. The Fraud Threat Has Fundamentally Changed
- Authentication: Controls at account opening and during high-value transactions must reflect today's threat environment, not protocols from five years ago.
- Staff training: Social engineering remains among the most common fraud entry points. Training must be ongoing and scenario-tested, not an annual checkbox.
- Member education: Clear, practical member education can reduce susceptibility to social engineering. Make it a standing part of the fraud-prevention program.
6. Revenue Diversification Must Be Earned, Not Extracted
7. Efficiency That Hurts Members Is Not Efficiency
Common Pitfalls to Avoid
- Treating AI as a technology project. AI value depends on accessible, trustworthy data and connected workflows, not on buying a model or running a pilot. The Financial Brand study found executives' confidence in AI readiness was only weakly aligned with their institutions' actual data foundations.
- Connecting to faster payments without updating controls. Instant finality requires fraud monitoring designed for seconds, not hours. FedNow's rapid participation growth makes operational readiness increasingly urgent.
- Measuring efficiency only by cost. An initiative that reduces internal effort but adds member friction creates attrition risk, not competitive advantage.
- Chasing revenue that conflicts with mission. Opaque fees or partnerships that prioritize margin can damage trust that took years to build.
One Priority That Unlocks the Rest
Build a Plan Around What Matters Most
- What would most improve the member experience today?
- What operational or risk gap could cause the most damage in the next 12 to 18 months?
- What investment would create durable advantage rather than a short-term fix?